
A 10-year Treasury at 5.3% and a stock market at record highs aren’t supposed to happen in the same week, but they did in late September. The 10-year hadn’t hit such a level in more than two decades. Ask anyone in January whether both could be true by October, and they’d have said rates that high would drag stock prices down with them.
Strange conditions tempt operators into second-guessing the basics, but every hero’s journey ends with a return back home to take up ordinary life again.
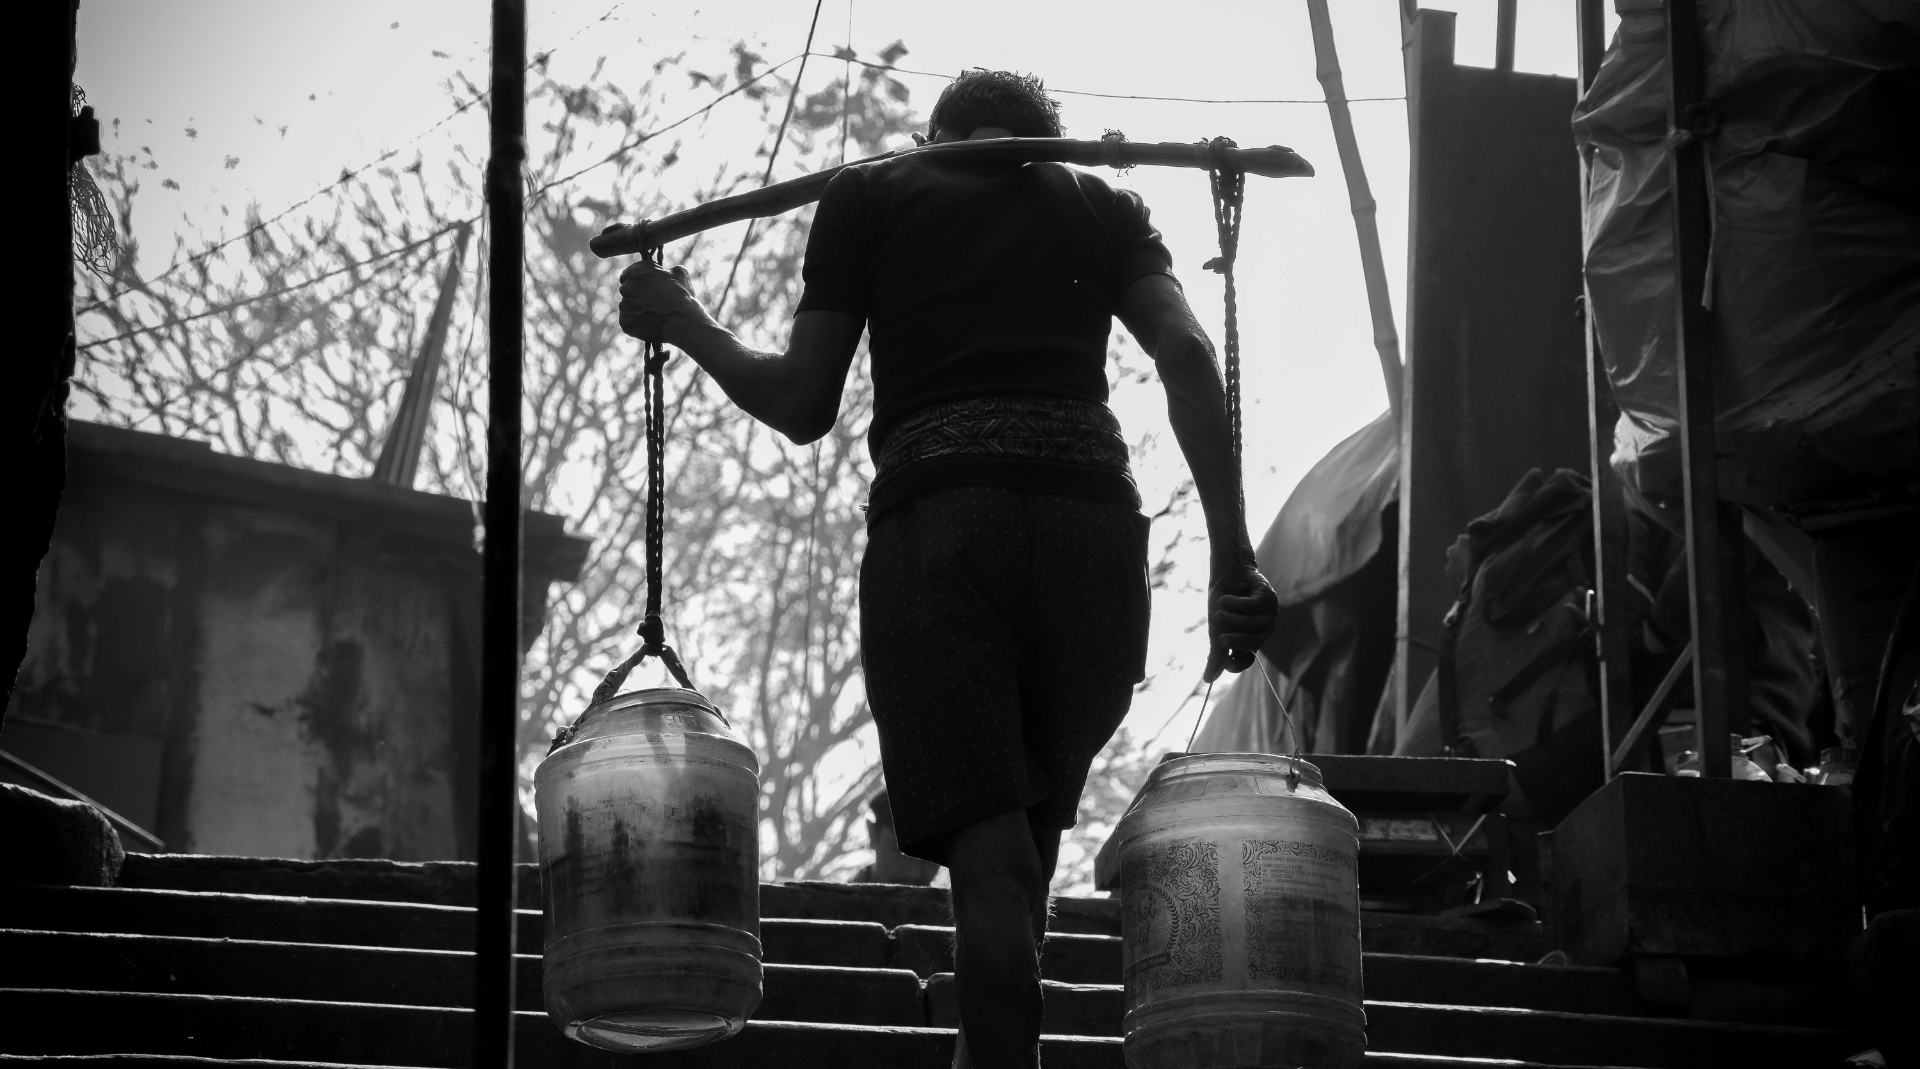
The Zen version is shorter: before enlightenment, chop wood, carry water. After enlightenment, chop wood, carry water. The student expects enlightenment to change the chores, when in reality, the only thing it changes is the student.
Before we pick the axe back up, here’s a look at the conditions we’re working in, where the risk in banking has moved, and why community banks keep calling us about the same customer.
The Benchmark’s Blind Spot
The stock market and the economy underneath it have drifted pretty far apart. The Wilshire 5000 covers every public company in the country, and its combined market value now runs about 234% of U.S. gross domestic product. The two tracked each other for decades.
The average stock in the S&P 500 is having a much worse year than the index lets on. It sits roughly 20% below its high for the year, and about 8% of the index is down 40% or more. Half the money in an S&P 500 fund goes into just twenty companies. Their gains offset the losses in the other 480 and hold the headline number up.
One part of the economy is booming, with data center spending running far ahead of general office construction. The suppliers feeding that buildout are doing well, but most of the country sits outside those benefits.
The divide runs through household balance sheets, too. The wealthiest 10% of American households own roughly 87% of the stock market, accounting for close to half of all consumer spending.
A rising market lifts spending power at the top. Lower down, credit card balances have climbed to $1.26 trillion, and new delinquencies on cards and auto loans remain elevated.
The Gift at 5%
A 10-year yielding north of 5% changes the math on long bonds. At today’s coupons, a 1% rise in rates costs a holder about 1.6%, and a 1% fall earns more than 12%. A fat coupon cushions the downside while the upside stays wide open.
Money is already moving on that math, with long-dated Treasury ETFs, broad Treasury funds, and muni bond funds all hitting records or multi-year highs in recent weeks. Managers who spent years telling clients to stay short now say they’ll look at longer duration in the next four to six months.
We still expect long rates to come down from here. The inflation data underneath the headlines keeps pointing that way, but getting the direction right and getting the timing right are two different animals.
Loans to the Lenders
Regulators are now taking a hard look at who really carries the risk in business lending. The New York Fed has spent recent months visiting the largest banks to ask how much they’ve lent to private credit firms, how they manage the exposure, and what collateral stands behind it.
After 2008, regulators barred banks from making certain risky loans, and a large non-bank lending industry rose up to make them instead. When those firms ran short of capital, they borrowed from the same banks that were barred from making the loans directly, which is perfectly legal.
The risk never left the system, and it now sits one step removed from the balance sheet examiners watch most closely. Any bank looking at its own pipeline is asking a version of the Fed’s question: what are we holding, and do we understand it?
Hitting the Easy Button
Community banks make nearly 60% of U.S. small business loans under $1 million. In one in five American counties, a community bank is the only physical bank there is. They see the small-business economy earlier than anyone, and they turn down good customers constantly.
Say a business owner has banked with you for ten years. He starts a new company and comes to you first, because of course he does. Two years of financials don’t exist yet, so the answer is no. He goes to a merchant cash advance shop or the bank one town over, and the relationship you spent ten years building goes with him.
There’s an Easy Button for this. Dare’s Back Room Service was built to make that answer a “yes.” The bank originates the deal and keeps the customer, and the facility books in its name on its own balance sheet. Dare handles underwriting, documentation, verification, servicing, and portfolio management.
Risk and reward split fifty-fifty, there’s no platform to license, and a program goes live in about 30 days with one setup fee. Building that same capability in-house runs about half a million a year in salaries, software, and legal work before the first deal funds.
The customer also has somewhere to go as he grows. Factoring lets the bank underwrite the collateral and watch it in real time while the business builds bankable habits, and from there he graduates to an asset-based line, then to a conventional line, with the same bank and the same officer.
The structure runs in reverse, too. A line-of-credit borrower who weakens and draws examiner attention can move into a factoring facility and get rehabbed inside the relationship.
Back to the Woodpile
Whatever the 10-year does next, somebody still has to decide whether a given debtor is good for a given invoice. A Fed review doesn’t settle that, and neither does an index at record highs or next month’s inflation print. The answer sits in the paperwork, the verification call, and the payment history.
This quarter did change where we look first. A debtor selling into the data center buildout is in a stronger spot than one selling to households drawing down savings, and that gap gets more of our attention than it did a year ago.
But the questions on each file haven’t moved an inch. Tomorrow morning, there’ll be invoices to verify and debtors to check, same as there were in September. Chop wood, carry water.
Want to say yes to more of your own customers?
As a Dare Back Room Service partner, you’ll get access to:
- Greater Income (like a lot more)
- Owning assets instead of commissions
- Zero investment down
- No personal liability
- Fifty-fifty split on risks and profits
- Portfolio management software from NN6, LLC
Want to learn more? Give us a call.
If you enjoyed this newsletter, pass it along to your friends.
Until next time,